About Me
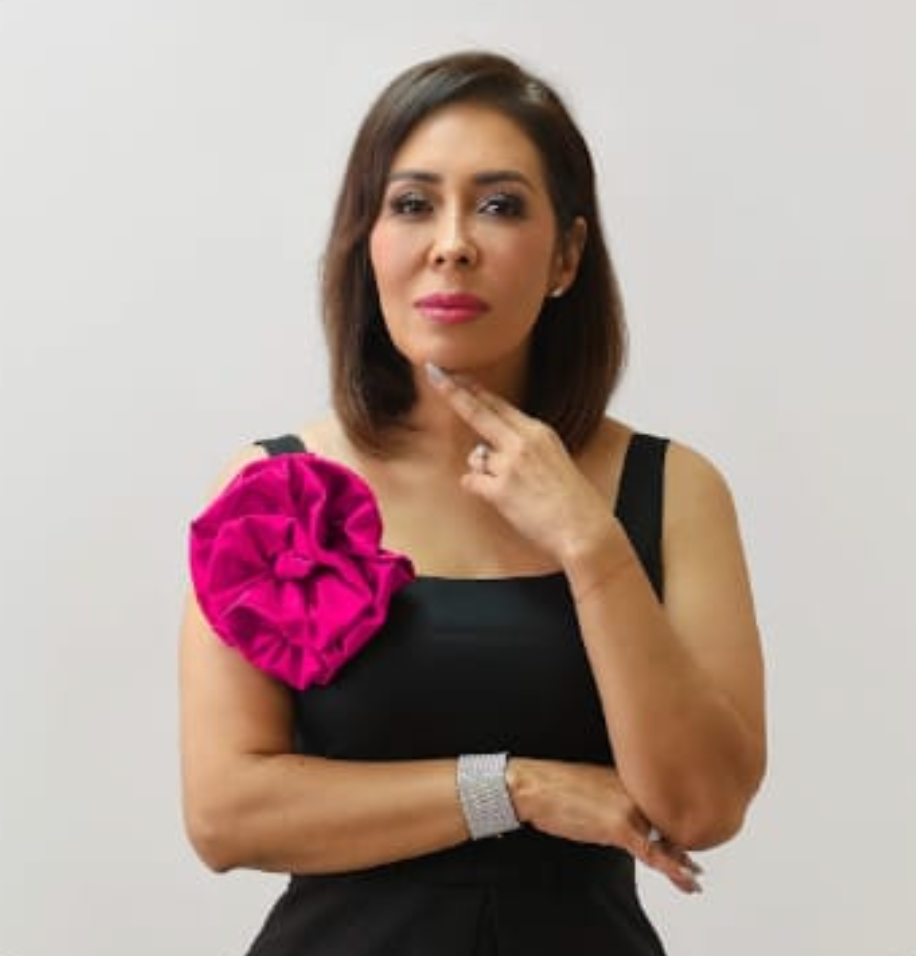
Meet Victoria Olivia Isais — a powerhouse of positive energy, real estate savvy, and client-first dedication. Victoria is not your average agent; she’s a passionate go-getter who truly loves what she does. Whether you're buying your first home, upgrading, or selling with big goals in mind, she brings unmatched enthusiasm and knowledge to the table. With a unique blend of traditional values and modern strategies, Victoria puts you first —your needs, your timeline, and your peace of mind. She listens carefully, communicates clearly, and works tirelessly to make your real estate journey feel effortless (and even fun!).
Victoria knows buying or selling a home is a big deal—emotionally, financially, and logistically. That’s why she’s right there beside you every step of the way, offering guidance, confidence, and, yes, a little humor when needed. She believes that with the right mindset (and the right agent), anything is possible — including your next move. With values rooted in loyalty, integrity, and hustle, Victoria Olivia Isais is here to help you reach your real estate goals and feel great doing it.
As an experienced mortgage lender in El Paso, TX, we'll guide you through the mortgage process. Whether you are a first-time homebuyer, a current homeowner looking to refinance, or looking to add an investment property to your rental portfolio, we deliver a five-star customer experience. SecurityNational Mortgage offers competitive interest rates and a wide range of loan products, from fixed-rate conventional mortgages to FHA, VA, and Jumbo loans, plus down-payment assistance programs. NMLS# 321753 Co. NMLS# 3116
Houses Sold
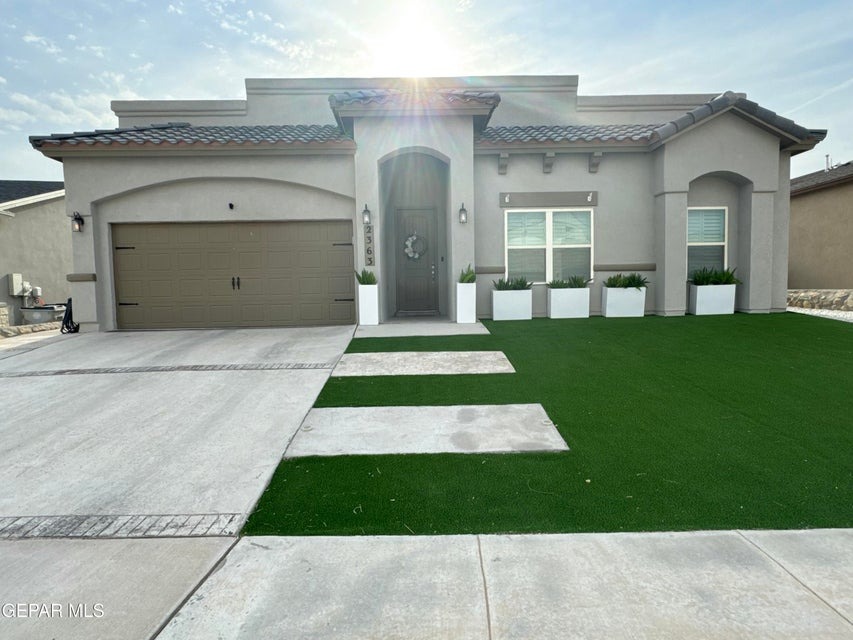
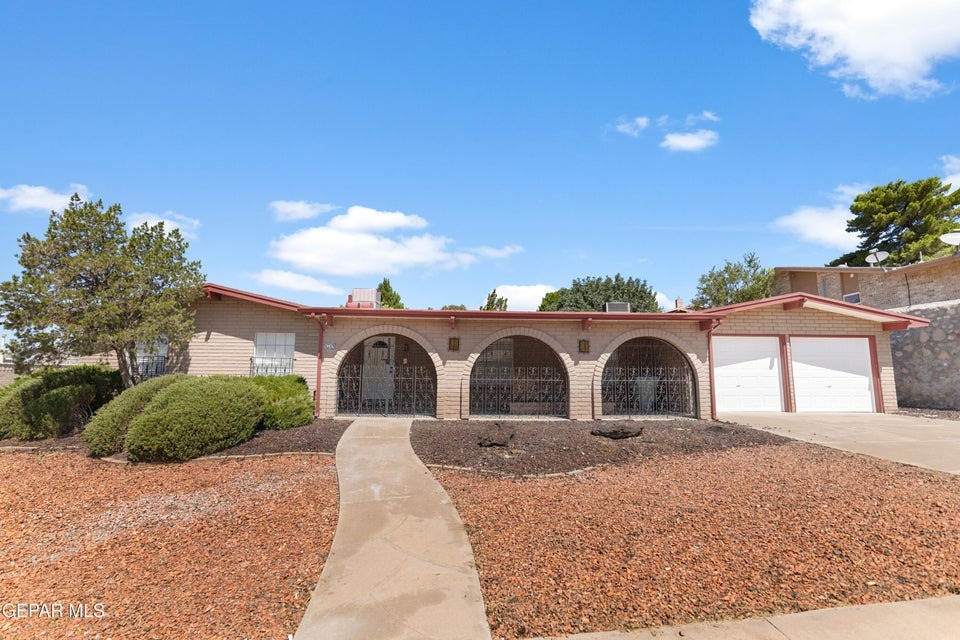
2363 ENCHANTED PEAKS
El Paso, TX 79911
SOLD PRICE $486,500
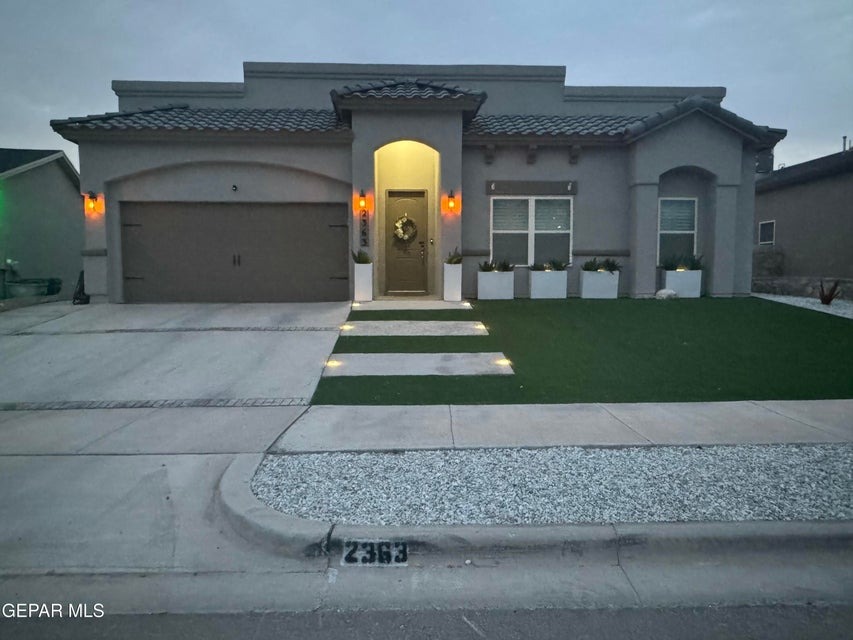
6249 BANDOLERO Drive
El Paso, TX 79912
SOLD PRICE $431,000
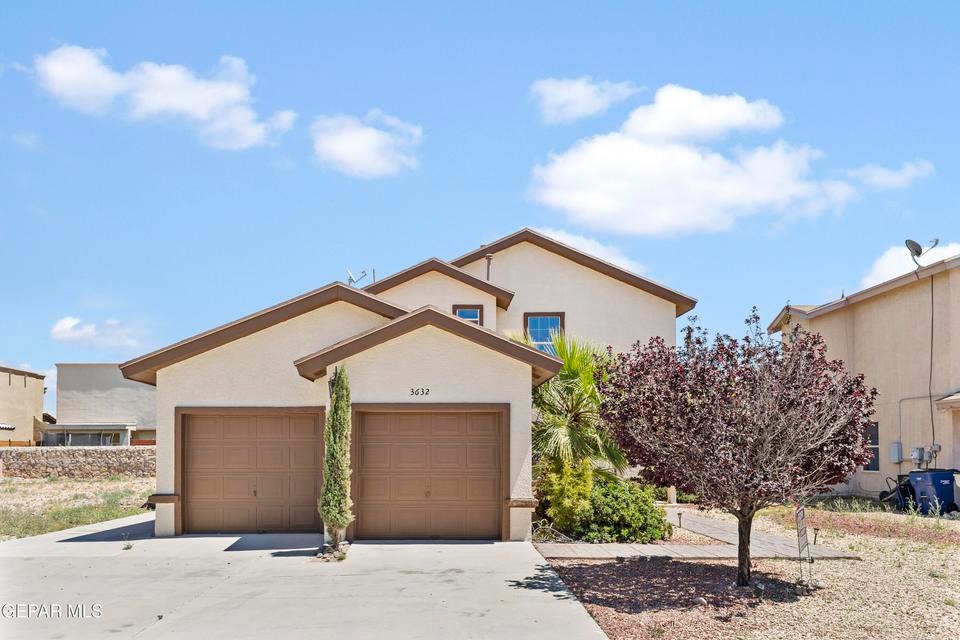
3632 JAMAICAN PALM Drive
El Paso, TX 79936
SOLD PRICE $241,000
3632 JAMAICAN PALM Drive
El Paso, TX 79936
SOLD PRICE $241,000
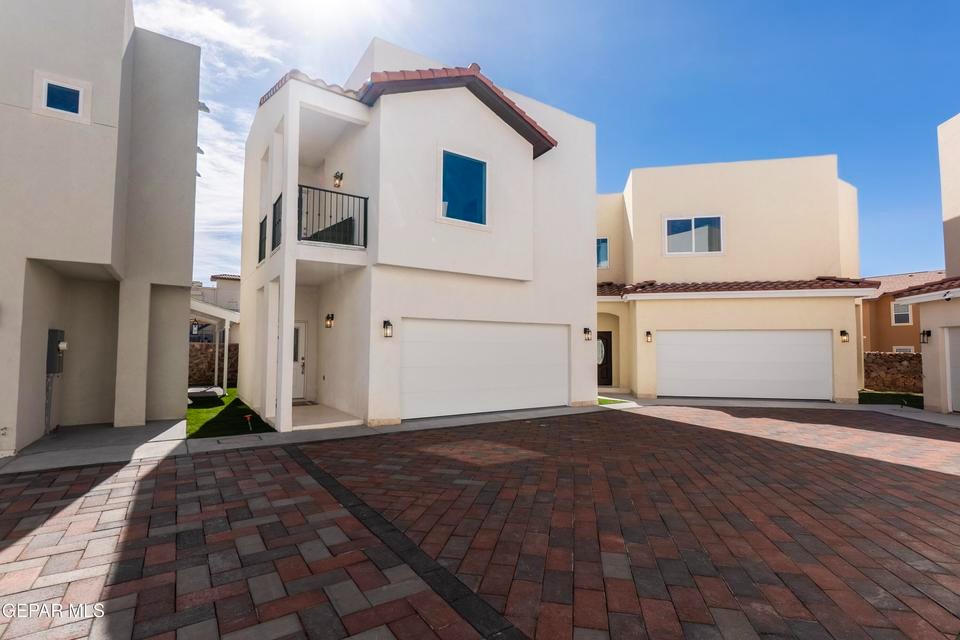
12241 GAUDI Way
El Paso, TX 79938
SOLD PRICE $275,000
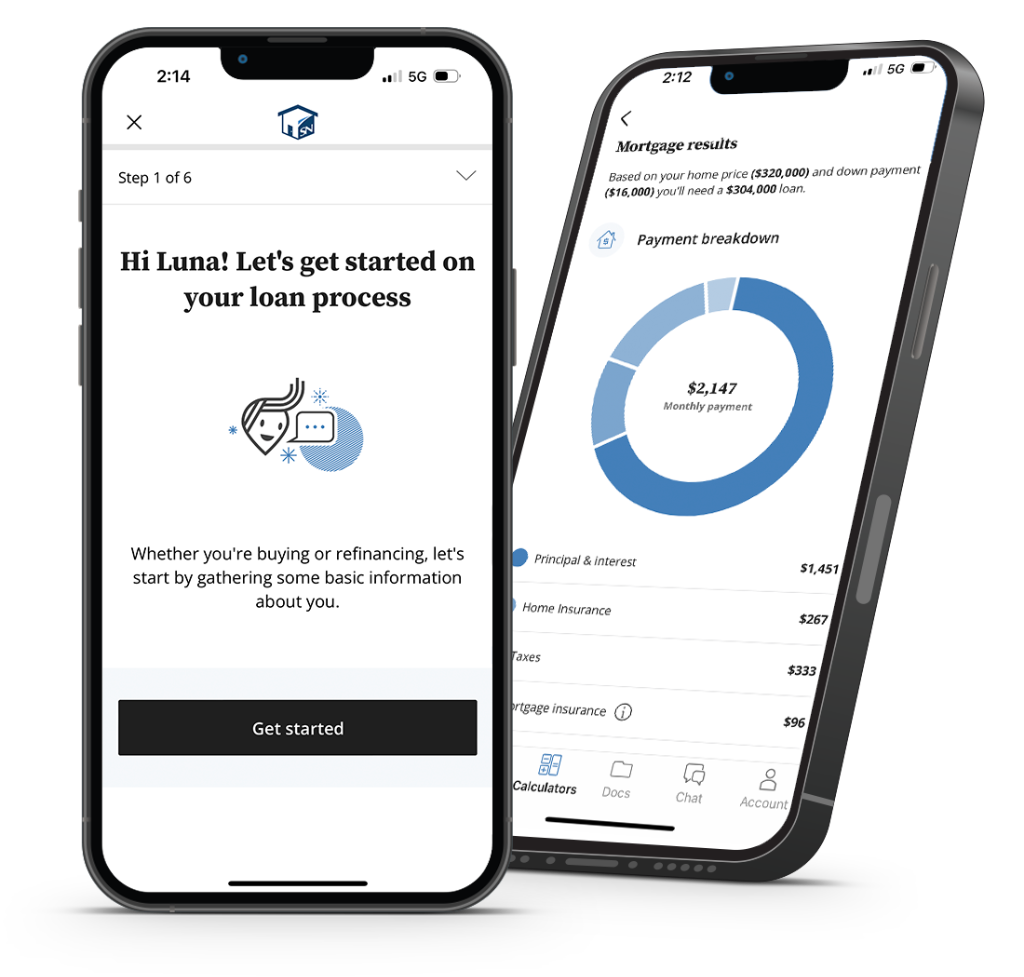
Start your home search today!
- Get instant updates at every milestone
- Sign documents securely from your phone
- Message your loan officer in seconds
- Submit financial documents in one tap


Mortgage Loan Frequently Asked Questions
What does mortgage pre-qualification involve?
Pre-qualification serves as the initial assessment in the home financing journey. By reviewing an unverified summary of your earnings, assets, and existing liabilities, a lender calculates an estimated borrowing limit. Because eligibility criteria—such as minimum credit thresholds, debt-to-income limits, and down payment sizes—differ by loan product, it is wise to assess your standing across several programs.
Keep in mind that pre-qualification is strictly an informal estimate. It carries little weight with sellers and will not strengthen an offer during negotiations. Complete approval requires in-depth verification of your job history, income sources, active liens, credit file, and the physical condition of the property itself. To enter the housing market with genuine purchasing power and a clear budget, obtaining a formal pre-approval early on is strongly recommended.
Are there fees associated with submitting a mortgage application?
Applying is typically free, though some lenders collect a nominal fee to pull your credit report. Any subsequent out-of-pocket expenses—such as home appraisal charges or formal processing fees—must be fully outlined in advance. These are only collected after you review your initial loan disclosures and formally confirm your intent to proceed.
What is the typical turnaround time for a mortgage?
Finalizing a mortgage generally spans between 10 and 45 days. The exact duration hinges on the loan category, underwriting requirements, and how straightforward your financial profile is to verify.
At what point can an interest rate be locked?
A rate lock typically becomes available once an offer on a specific home has been formally accepted by the seller. Your loan advisor will review the available lock strategies and timing with you during the early stages of application processing.
How long does an interest rate lock remain active?
Rate commitments generally remain valid for periods ranging from 15 to 180 days, determined by your expected closing schedule and the specific requirements of the transaction.
Is refinancing the right financial move?
Deciding to refinance involves balancing several economic factors. Even a slight drop in interest rates can lower recurring monthly payments, but your actual net gain depends on the remaining loan balance, upfront closing fees, and your long-term plans for the property. A qualified mortgage advisor can model multiple payment scenarios to see if refinancing yields a net positive return. You should also consult a tax professional to evaluate any tax implications tied to your mortgage structure.
What documentation is provided during the closing process?
During closing, you will review and execute all legal, binding instruments related to the property transfer and financing. Once signed, duplicates of every document are provided for your records before the originals are submitted to local public registries. You will also receive an itemized schedule detailing your monthly payment structure, upcoming due dates, and servicing transfer instructions.
Can buyers secure home financing with a history of credit issues?
Securing a mortgage is still viable following credit setbacks, though options will carry tighter terms. Lenders offset the elevated default risk by requiring larger upfront down payments and charging higher interest rates. Underwriting tolerances vary widely across the industry, meaning some institutions decline credit-challenged files entirely while others specialize in them. Consulting directly with a loan professional helps identify immediate loan options or establish a targeted plan to rebuild your credit profile before purchasing.
Contact Me
Have questions or ready to get started? Send me a message and securely upload your documents below.
SecurityNational Mortgage Company #321753
SecurityNational Mortgage Company is a mortgage lender serving homebuyers and homeowners in El Paso, TX, offering conventional loans, FHA loans, VA loans, USDA loans, Jumbo loans, Non-QM loans, and construction loans.
Looking for mortgage lenders in El Paso, TX? Located at 1600 Lee Trevino, SecurityNational Mortgage in El Paso is here to help you find the right mortgage loan for your unique situation, with the personal service and local expertise you deserve. We offer conventional loans, FHA loans, VA loans, USDA loans, Jumbo loans, and Non-QM loans, as well as down payment assistance programs, refinance options, cash-out refinancing, ITIN loans, investment property financing, homebuilder loans, and one-time close construction loans.
In addition to El Paso, our team proudly serves homebuyers and homeowners and the surrounding communities.
Whether you're starting your mortgage pre-approval, buying your first home, refinancing an existing loan, or exploring investment property financing, our experienced El Paso loan officers will take the time to understand your goals and match you with the right loan program at a competitive rate. When you're searching for mortgages near me or comparing mortgage lenders near me, SecurityNational Mortgage in El Paso puts borrowers first, backed by over 30 years of experience and the financial strength of Security National Financial Corporation (NASDAQ: SNFCA). Our El Paso loan officers are active members of the community, invested in helping the people who call El Paso home achieve lasting homeownership.
SecurityNational Mortgage has earned an average rating of 4.97 out of 5 stars across more than 5,000 Google reviews nationwide. Our El Paso customers trust us to deliver a five-star mortgage experience from application to closing.
Stay connected with your loan officer and manage your loan anytime with SNapp, our easy-to-use mortgage app. At SecurityNational Mortgage, we have one goal: Turning Houses into Homes.
What Every Buyer Should Know Before House Shopping
How much are property taxes in El Paso, and how will they affect my monthly payment?
Property taxes in El Paso County typically range from about 2.1% to 2.8% of the assessed value, depending on your school district (EPISD, SISD, YISD, etc.) and municipal boundaries (such as City of El Paso, Socorro, or Horizon City). Because Texas has no state income tax, property taxes make up a substantial portion of your monthly escrow payment. As your buyer's agent, I will calculate estimates based on current local tax entities and guide you through filing for the Texas General Residence Homestead Exemption once you close to reduce your taxable value.
What is the Texas "Option Period," and how does it protect me?
In the standard Texas Real Estate Commission (TREC) contract, the option period is an agreed-upon window (typically 5 to 10 days) for which you pay the seller an upfront option fee (usually $100 to $250). During this timeframe, you have the unrestricted right to terminate the contract for any reason and retain your earnest money. This is the critical window when we schedule your home inspection and negotiate any requested repairs or price concessions.
Does the home have refrigerated air conditioning or an evaporative ("swamp") cooler?
In the desert climate of the Sun City, cooling systems are a primary focal point. Older homes often feature evaporative cooling, which relies on water evaporation and struggles during monsoon season when humidity rises. Newer builds and updated properties feature refrigerated air (central A/C). If a home you like has a swamp cooler, we can explore conversion costs (typically $6,000 to $12,000) or negotiate seller concessions toward the upgrade.
I am PCSing to Fort Bliss. Can I buy a home with a VA loan remotely?
Yes. El Paso has a very military-friendly market, and we frequently handle remote purchases for service members stationed at Fort Bliss. We conduct high-definition video walkthroughs, coordinate local inspectors familiar with VA Minimum Property Requirements (MPRs), and work alongside VA-specialized lenders. Texas also offers significant property tax exemptions for disabled veterans based on their VA disability rating.
What are the major differences between living on the Westside, Eastside, Northeast, and Far East?
Westside: Characterized by proximity to the Franklin Mountains, older custom estates, dramatic sunset views, and easy access to UTEP and Downtown via I-10 or Transmountain Road.
Eastside & Far East (Horizon / Socorro): The fastest-growing corridor in the region, offering the largest selection of new-construction subdivisions, master-planned communities, parks, and major retail centers.
Northeast: Highly convenient for quick gate access to Fort Bliss, featuring established neighborhoods, more affordable entry-level pricing, and sweeping mountain scenery.
Are there first-time homebuyer or down payment assistance programs available locally?
Yes. Beyond federal programs (FHA at 3.5% down, USDA at 0% down in eligible outlying zones, and VA at 0% down), local buyers can utilize programs from the El Paso Housing Finance Corporation (EPHFC)—such as the Welcome Home and Mi Casa grant programs—as well as state-level programs through TSAHC and TDHCA. These programs offer grants and forgivable second liens to help cover down payments and closing costs for qualifying income levels.
How much earnest money and closing costs do I need to budget for?
Earnest Money: Typically 1% of the purchase price, deposited with the title company within three business days of going under contract to demonstrate good faith.
Closing Costs: Usually run between 2% and 4% of the loan amount (covering lender origination, appraisal, title policy fees, pre-paid taxes, and homeowner’s insurance). In many negotiations, we can ask the seller for closing cost contributions to reduce your out-of-pocket expenses.
Who pays the title policy and survey fees in an El Paso transaction?
Under Texas residential contracts, these costs are negotiable, but local market customs strongly influence who covers them:
Owner’s Title Policy: It is common in El Paso for the seller to pay for the owner’s title policy, though this depends on market conditions and contract terms.
Property Survey: If the seller does not possess an existing, notarized survey acceptable to your lender and title company, either party can agree to purchase a new one (usually $400 to $650).
What should I look out for during a home inspection in this region?
Beyond standard plumbing, roof, and electrical evaluations, El Paso inspections require specific attention to:
Soil movement & foundation integrity: Desert soil expansion and hillside grading along the mountains can cause settlement cracks.
Roof condition: Flat or low-slope roofs common in Southwestern architecture require routine maintenance, while asphalt shingle roofs need evaluation for hail and wind damage.
Termite/WDI (Wood-Destroying Insect) report: Even in the desert, subterranean termites exist; lenders often mandate this inspection.
Does the home have a rock wall boundary, and who is responsible for maintaining it?
Most residential lots in El Paso are enclosed by cinder block or native rock walls rather than wooden privacy fences. When a wall sits directly on the boundary line between two properties, maintenance responsibility is shared equally by both neighbors. During the title and survey review, we verify whether walls encroach over lot lines, utility easements, or drainage corridors.
How long does it take from getting pre-approved to receiving the keys?
The overall timeline generally ranges from 30 to 60 days:
Home search & contract offer: 1 to 3 weeks on average, depending on inventory.
Contract-to-close period: Typically 30 to 45 days for conventional, FHA, or VA financing (or 10 to 14 days for all-cash purchases). This period allows ample time for underwriting, appraisal, title search, and final closing at the title company.
What Every Home Seller Should Know Before Listing
How much will it cost me to sell my home, and what does a "Seller Net Sheet" show?
In El Paso, overall selling costs generally range between 6% and 8% of the final sale price. These costs include negotiated broker commissions, the owner’s title policy, escrow settlement fees, and property tax prorations.
Texas does not charge a real estate transfer tax, which saves you money compared to many other states. Before listing, I will provide a Seller Net Sheet that factors in your anticipated sale price, estimated closing fees, and your current mortgage payoff balance to show you exactly what cash proceeds you will walk away with at closing.
Is it worth converting my evaporative cooler to refrigerated air before selling?
Yes, in the El Paso market, refrigerated air is often the single most requested upgrade from buyers. Homes with central refrigerated A/C sell significantly faster and command higher per-square-foot offers compared to those relying on evaporative ("swamp") coolers, which struggle during humid monsoon weeks in July and August.
While a full conversion typically costs between $6,000 and $12,000, you usually recoup a major portion of that cost in your list price and avoid buyers requesting heavy repair concessions during the inspection phase. If you choose not to convert upfront, we can price the home accordingly or offer a buyer credit.
By local custom, do sellers in El Paso pay for the buyer's Title Policy and Survey?
Under the standard Texas Real Estate Commission (TREC) contract, all closing costs are legally negotiable. However, local El Paso custom plays a major role:
Owner’s Title Policy: It is customary for the seller to pay for the buyer’s title insurance policy. Title policy premiums are strictly regulated and standardized by the Texas Department of Insurance (TDI) based on purchase price.
Existing Survey & T-47 Affidavit: If you have your original boundary survey, you can sign a notarized Residential Real Property Affidavit (Form T-47) confirming you haven’t made structural changes (like building a new patio, shed, or rock wall extension). This allows the buyer's lender to reuse your survey, saving you or the buyer roughly $450 to $650 for a new one.
How are El Paso property taxes handled at the closing table?
Texas property taxes are paid in arrears (billed each October and delinquent after January 31 of the following year).
Because you occupy the home for part of the tax year before closing, you will credit the buyer a prorated portion of the year’s property taxes at the closing table (from January 1 up to the exact closing date). Once the full annual tax bill arrives later in the year, the buyer uses those credited funds—combined with their own escrow payments—to pay the county tax assessor.
What legal disclosures am I required to provide under Texas law?
Under Texas Property Code § 5.008, sellers must complete and sign the Texas Seller’s Disclosure Notice. This document legally requires you to disclose all known conditions and material defects regarding the property, including:
- Roof condition, past leaks, and previous hail or wind insurance claims
- Any history of foundation settling or soil shifting
- Past plumbing leaks, sewer line backups, or polybutylene piping
- Functionality of appliances, electrical systems, and heating/cooling units
Being completely transparent protects you from post-closing liability and reduces the risk of deals collapsing during the buyer's option period.
Many buyers here use VA loans. Will my home have to pass special VA appraisal guidelines?
Because of nearby Fort Bliss, active-duty and veteran buyers represent a large segment of the El Paso market. The VA appraisal includes Minimum Property Requirements (MPRs) focusing on health, safety, and structural soundness.
To pass without costly re-inspections, we will pre-screen your property for common VA flags before listing:
- No peeling or chipping exterior/interior paint (especially homes built before 1978)
- Operational heating/cooling equipment with safe access
- Secure handrails on staircases or elevated porches
- Intact roof coverings with a remaining useful life of at least two years
- Operational double-paned or weather-stripped windows
What happens during the buyer’s "Option Period," and do I have to make every requested repair?
In Texas, the buyer pays you an Option Fee (typically $100 to $250) for the unrestricted right to terminate the contract within an agreed window (usually 5 to 10 days) while conducting home, roof, and termite (WDI) inspections.
You are not legally obligated to make any requested repairs. When a buyer submits a repair amendment, we have three strategic choices:
1. Agree to complete specific repairs using licensed contractors before closing.
2. Offer a negotiated closing cost credit or price reduction in lieu of repairs.
3. Decline the request entirely if the demand is unreasonable or the property is priced to reflect its current condition.
What exterior improvements deliver the best return on investment in our desert climate?
First impressions matter, particularly in the Chihuahuan Desert landscape. High-ROI exterior updates include:
Rock wall tuck-pointing & repairs: Repairing cracked cinder blocks, mortar joints, or perimeter stone walls.
Xeriscape cleanup: Adding fresh desert gravel or red volcanic crushed stone, trimming native yucca and palm trees, and clearing weeds.
Front entry refresh: Power washing stucco, restaining or painting sun-faded front doors, and replacing tarnished house numbers and exterior lighting.
When is the best time of year to list a home in El Paso?
While spring (March through June) is traditionally active, El Paso benefits from a steady year-round military relocation cycle driven by Fort Bliss summer and winter PCS (Permanent Change of Station) orders.
Listing in late spring captures military families moving before the start of the EPISD and Socorro ISD school years, while late autumn and early winter see low listing inventory, meaning serious buyers face less competition.
Can I sell my home if I currently have a tenant living in it?
Yes, but the strategy depends on their lease status:
Active Fixed Lease: In Texas, the lease agreement transfers with the sale. The buyer must honor the existing lease terms and rental rate through expiration. This arrangement appeals mainly to real estate investors.
Month-to-Month Lease: We can provide the tenant with standard written notice to vacate according to Texas law if you want to sell to an owner-occupant buyer.
Alternatively, if you sell with the tenant in place, we coordinate specific showing windows and verify that tenant security deposits and prorated rents transfer seamlessly to the buyer at escrow.
Can I stay in my home for a few days after closing?
Yes. If you need time to pack, move into a new property, or close on your next home, we can negotiate a TREC Seller’s Temporary Residential Lease (commonly referred to as a "leaseback").
This legal addendum allows you to remain in the property for up to 90 days after closing and funding as a temporary tenant of the buyer, paying an agreed daily rental rate and security deposit. It gives you immediate access to your sale proceeds while providing breathing room for your move.